
The objective of this Investing 101 series is to give you the basics on how to invest.
This piece is also available in 3 parts, with a link for the first one.
This article will follow the format I use in my deep dives. It will consider a business review covering the products and services sold by the company, followed by an examination of the market structure and competitive advantage, followed by an assessment of the company’s life cycle and a review of market segments (such as quality, value, etc.). Then in the second part, the financial aspects, a management analysis, and capital allocation, and in the third and last part, an outlook based on bullish and bearish arguments and the company’s expected returns.
Here are the two first articles in case you missed it:
Part One - The business
1. Introduction
The first question to ask is: “What does the company sell? What products and services does the company offer?”
This is the core of the study, around which all other responses will revolve. It is therefore necessary for you to review the various products and services and the markets in which they are sold. This requires you to know what market shares they hold.
Obviously, a company does not operate in a vacuum; it is necessary to identify its environment—that is, its customers, suppliers, and competitors.
What are the company’s customers looking for in this product? How many are there? Do they purchase the product directly from the company or through a distributor? Does the company have a major customer that poses a risk?
As for suppliers, who are they? Is there a critical dependency on any of them, or does any of them have pricing power?
For competitors, we will seek to determine their market shares and their products.
Finally, at this stage, we can ask ourselves what ethical issues or risks the company faces. This is something I consider early enough in my research to rule out candidates who wouldn’t be a good fit for me.
Once you’ve taken this initial look at the big picture, the question to ask yourself comes back to the products: “Am I able to determine whether the company’s products or services are superior to those of the competition?”
That’s Peter Lynch’s famous “Invest in what you know.” If you can answer that question, great—you’re probably onto something. For example, in my own circle, I’ve noticed that the people I meet place a higher value on iPhones. That my kids, like everyone else, always prefer Coca-Cola to any other drink on earth. That if people had to keep just one streaming service, the majority would choose Netflix.
There are many excellent investment opportunities available to us as individual investors, and they do not require any special skills.
Conversely, if you are unable to determine whether the company outperforms its competitors based on anything other than the numbers, you will always have a hard time keeping your cool during a market downturn and forming a clear opinion about your investment.
A 2018 study by Hendrik Bessembinder titled “Do Stocks Outperform Treasury Bills?” indicates that, among stocks listed in the United States between 1926 and 2016 (approximately 25,300 securities), only about 4% of the securities accounted for all of the stock market’s net wealth creation over that period. The remaining 96% did no better than one-month Treasury bills (i.e., short-term U.S. bonds).
A follow-up study, expanded to include 62 countries over the period 1990–2020, found an even more concentrated result: 2.4% of the world’s publicly traded companies accounted for all $75.7 trillion in net stock market wealth creation during that period.
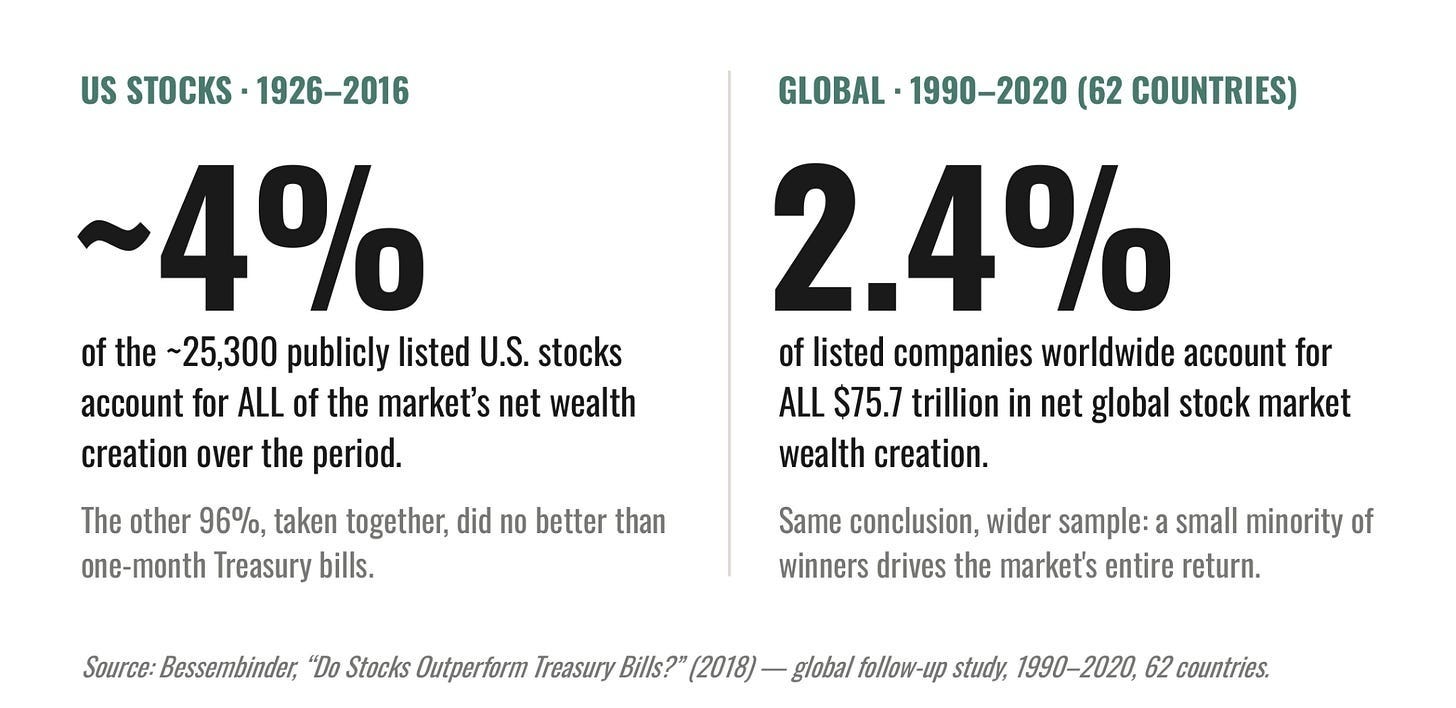
The takeaway from this point is that the stock market’s performance is driven by a very small number of winners and a myriad of losers. And it is these few companies that will be the gems of your portfolio.
These are companies that I refer to as “category definers,” because they have helped create a product category in which they dominate the competition—or better yet, have no competition at all.
This superiority stems in particular from the market structure and the differentiation these companies have succeeded in achieving in their market.
2. Market Structure
2.1 The Model of Pure and Perfect Competition
One of the first topics I studied as an undergraduate economics major was the model of pure and perfect competition, because it provides the framework within which many companies operate.
We’ll see why this model is the bane of shareholders. It has several characteristics:
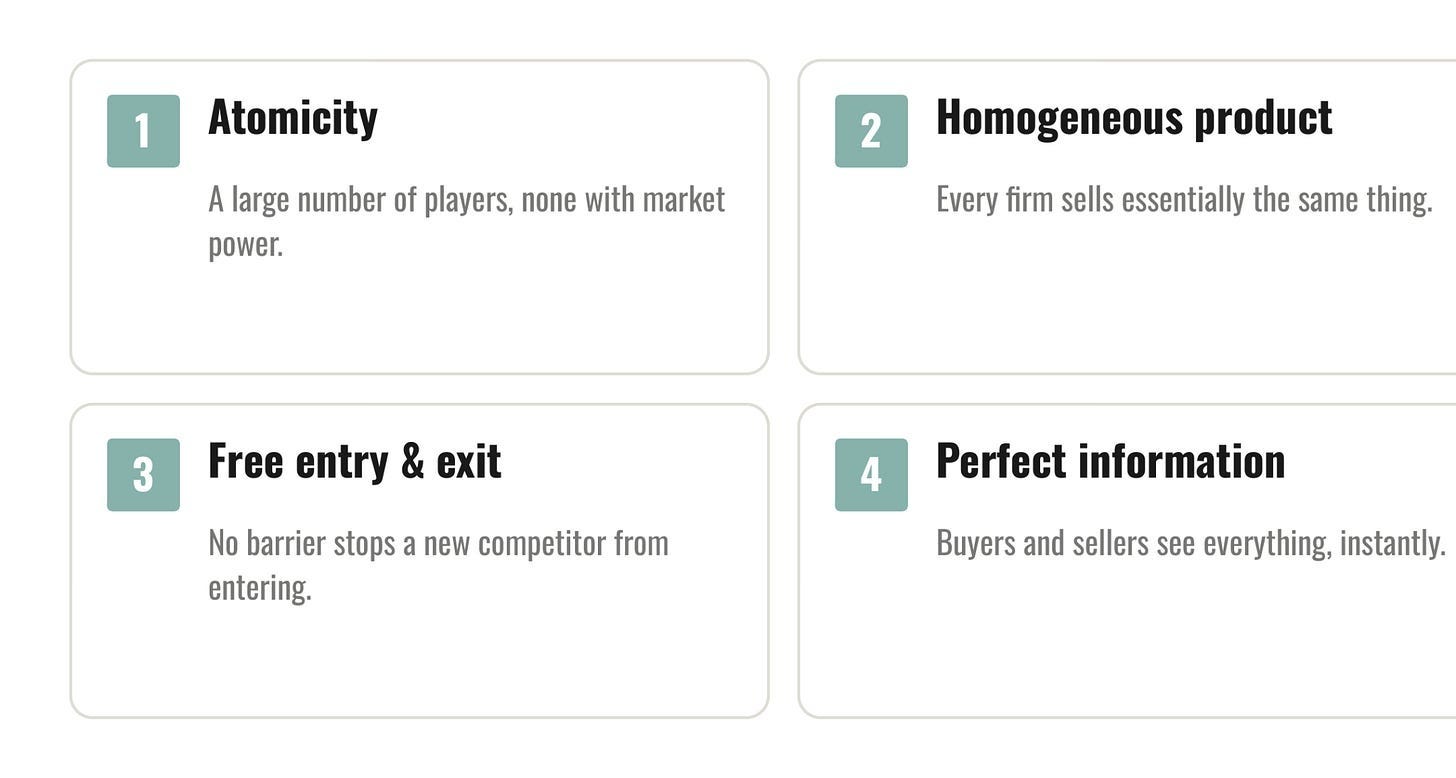
The implication of these four points is that, in this model, firms’ long-run profits tend toward zero, because any profit will attract competitors. Increased competition will drive prices down until producers go out of business, thereby restoring the equilibrium price. The price is therefore equal to the marginal cost (the cost of producing one additional unit), and the return on invested capital (ROIC) is equal to the WACC (the cost of capital).
Agricultural commodities such as bulk coffee, corn, wheat, and soybeans come close to this model: there are thousands of producers selling the same product in a market where anyone in the right climate can start growing that crop, and where price information is available on international markets. The foreign exchange (forex) market is also similar.
Every company will obviously seek to break free from this model, with varying degrees of success depending on the “imperfections” present in its market—which are referred to by the academic term “competitive advantage.” The most famous investor of all, Warren Buffett, coined the term moat to describe this concept, and it is now commonly used in the financial world. It is precisely because it is possible to break away from this model that individual investing makes sense.
Before examining the specific mechanism that enables this escape (the “moat,” discussed in more detail below), it is helpful to first determine where the company falls on the spectrum of market structures.
2.2 Market Structure: From Monopoly to Niche
On one end of the spectrum is the model of pure and perfect competition, and on the other end is the monopoly, which poses societal challenges. In between, there are several gradients worth exploring:
Monopoly : A single firm serves the market. Since users cannot find alternatives to the firm’s products and services, the firm’s bargaining power is disproportionate. The regulator typically seeks to regulate or break up this monopoly, or to turn it into a public utility. Monopolies often exist in the form of public utilities (Con Edison in New York, PG&E in California, and airports when there is only one at the local level, such as in Zurich or Florence). Often, this type of market is maintained when there is no practical reason to allow competition to enter.
Duopoly : Two dominant players share most of the market—for example, Visa and Mastercard in payment networks, or Airbus and Boeing in long-haul aircraft. They manage to coexist because neither has any interest in triggering a price war that would hurt both of them equally. This type of market is often very profitable for shareholders, and it is easy to track the market by following the two leading companies.
Oligopoly: A handful of players (usually 3 to 5) share a market with high barriers to entry—competition may be divided into market segments allocated to each player. The goal is always to avoid a price war, which would be costly for all players. It is also possible for all players to agree on a market price; this is known as a cartel. Such an agreement tends to draw the ire of regulators.
Niche market: a market that is too small, too specialized, or not glamorous enough to attract serious competitors—there’s no need for a legal monopoly or a patent; the market’s size or specialization itself acts as a barrier (no one bothers to enter a market whose potential is considered too limited)
Pure and perfect competition: no firm makes a profit.
The general rule to remember is that the best competition is no competition at all, or as little as possible.
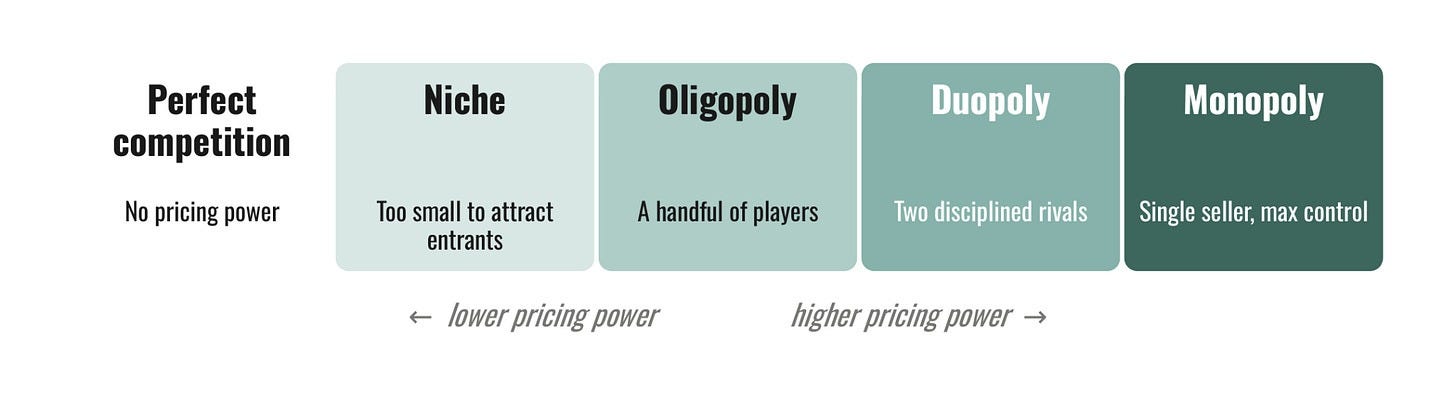
This classification provides a useful overview of the market and its existing players. We must now examine the reasons why new players cannot enter this market—that is, the company’s competitive advantage.
2.3 Competitive Advantage (Moat)
This article is not intended to be exhaustive on every point, so I will outline the main moats you should know about:
Switching costs: switching costs — it’s expensive or a hassle to leave,
Network effects: The product becomes more useful as more people use it
Brand: Customers pay more for the same product because of the name
Economies of scale: The largest product is structurally less expensive than the others because fixed costs are spread out
The difficulty of replicating a product
Regulatory or intangible assets: licenses, patents, rare permits.
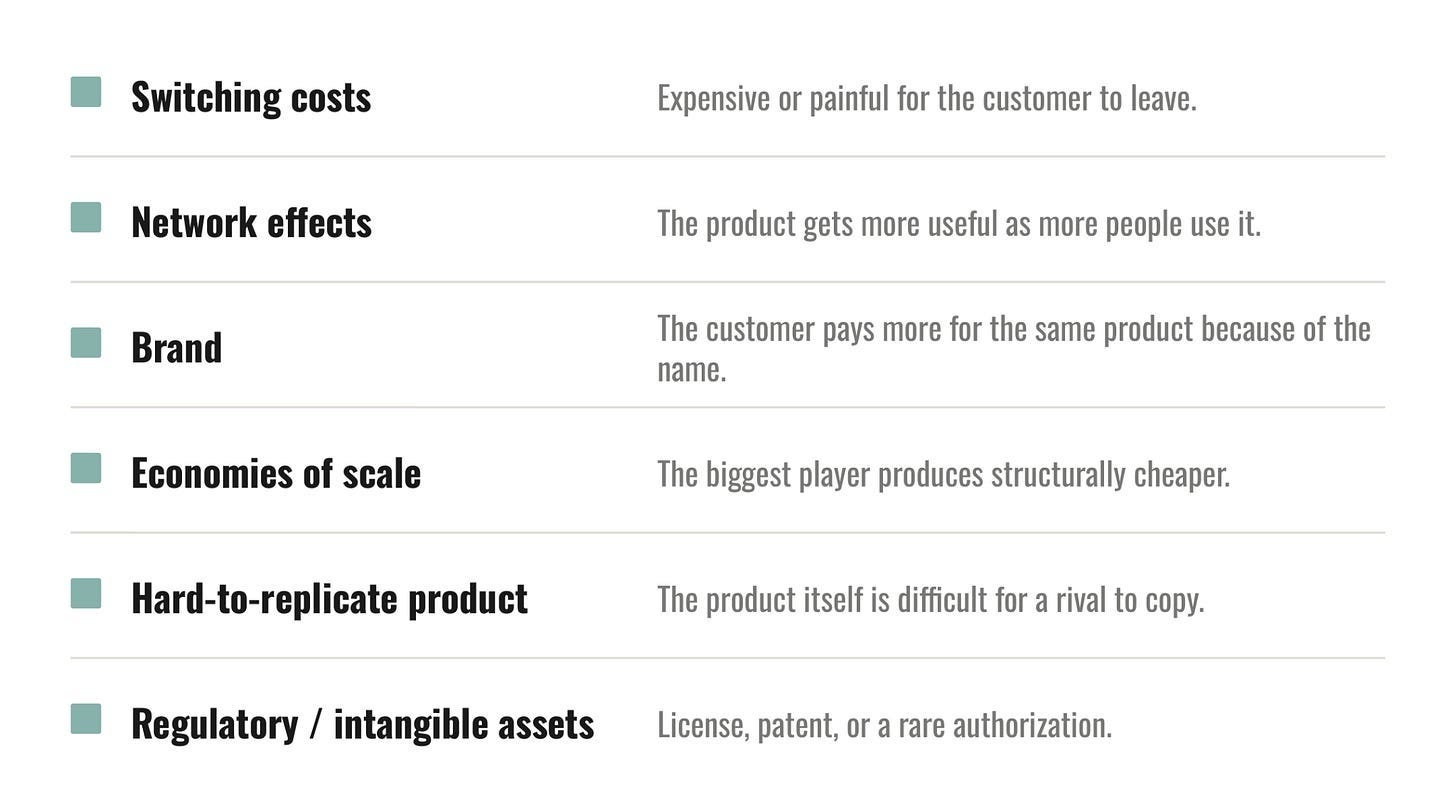
Often, the best companies have multiple competitive advantages that grow stronger over time
On the other hand, keep in mind that what can reshuffle the deck within the market is technological change, which is a double-edged sword: it can help established companies solidify their position—or work against them.
Let’s take Coca-Cola as an example. Consumers place a higher value on Coca-Cola by choosing it over a cheaper alternative. Decades of advertising and history have linked it, in the minds of consumers, to sporting events, sharing, and a polar bear. Behind this beverage lies the entire world of American soft power.
Yes, the product can be replicated by any chemist, but the name and visual identity remain protected by a trademark.
In terms of the costs of change, Coca-Cola has locked out the competition with distribution contracts that are unbeatable due to the volumes sold. At the local takeout restaurant, there’s often a Coca-Cola fridge. Doing without it would mean replacing the fridge (which is certainly sold at a competitive price), and doing without Coca-Cola products would mean cutting back on one of its easy sources of high-margin revenue. If you leave Western countries, your choices for non-alcoholic beverages will often be limited to water, local sodas, or products from the Coca-Cola lineup. The latter are therefore, by nature, much more competitive.
Competitors’ products can threaten the company through e-commerce, reaching consumers directly without going through a century-old distribution network. However, Coca-Cola can still try to acquire the most promising startups early in their development, before regulators block the merger to maintain competition in the market.
Warren Buffet a eu la phrase célèbre: “If you gave me $100 billion and said take away the soft drink leadership of Coca-Cola in the world, I’d give it back to you and say it can’t be done.”
It is important to note that a moat is built over time and that, by its very nature, a new company will not have one. Everything rests on the pillars of superior products and services and high-quality management.
3. Life Cycle and Framework for Analyzing the Initiative
3.1 The Life Cycle of a Business
A company can be viewed in an organic way, as having a life cycle: it starts small with a product or service, then grows and develops a business model that becomes increasingly efficient, enabling sustained growth over time. The business, which initially operates at a loss, eventually manages to turn a profit and sustain that profit over the long term. Growth is strong at first because the company is starting from a small base, then slows over time until it stabilizes. Finally, the decline phase begins, which can occur more or less rapidly depending on the nature of the business.
Aswath Damodaran, professor of corporate finance and valuation at New York University’s Stern School of Business, offers excellent resources, particularly on the corporate life cycle. The images below are taken from one of his articles:
The Corporate Life Cycle: Managing, Valuation and Investing Implications
2 years ago · 159 likes · 4 comments · Aswath Damodaran
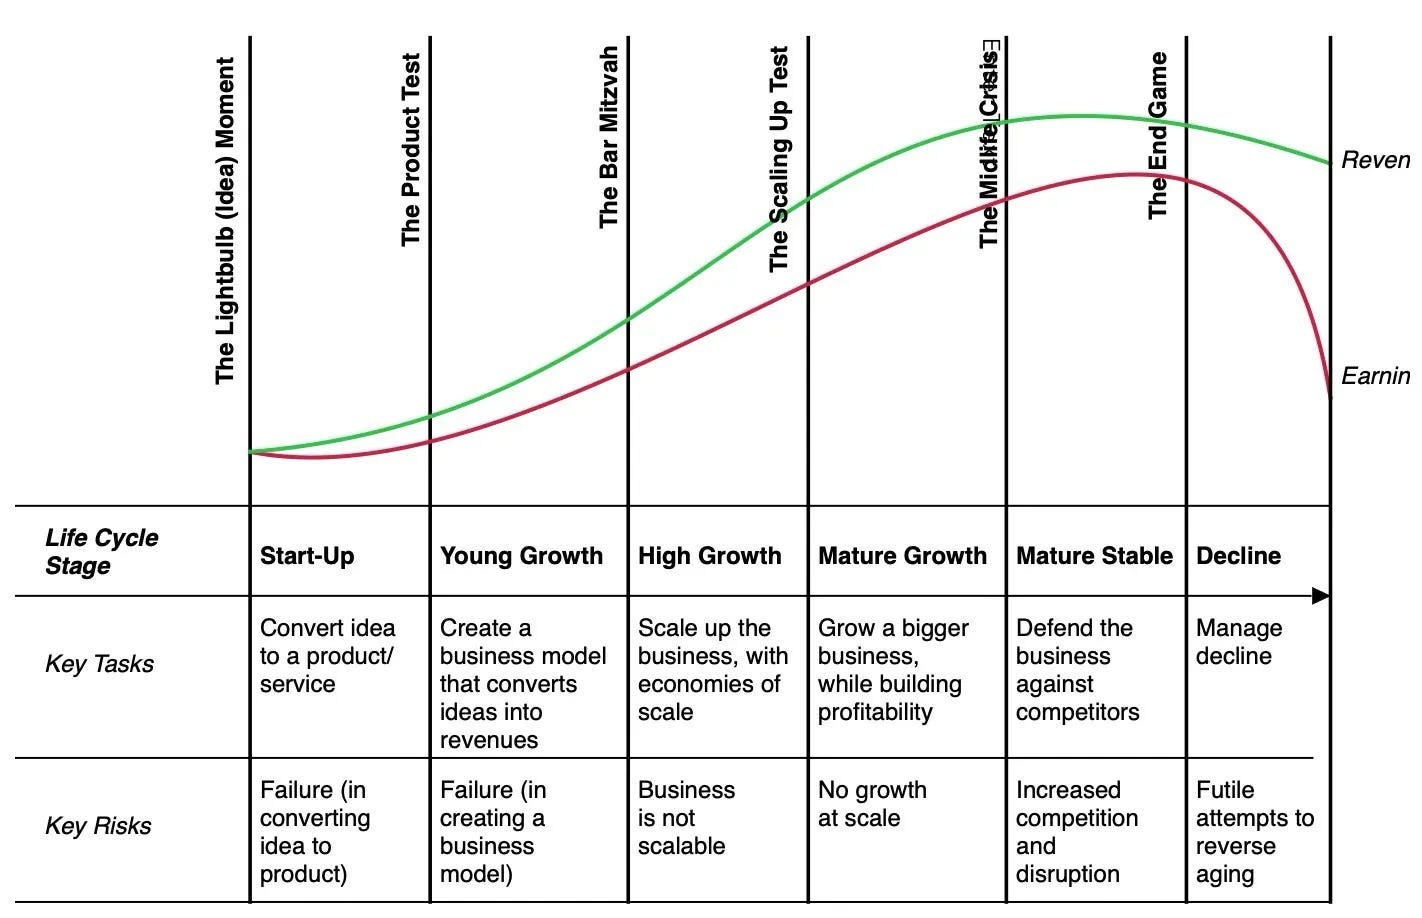
Depending on your experience and investor profile, you will likely develop preferences for certain investment life cycles, styles, or factors.
3.2 Investment Styles
We often hear about Quality, Value, and Growth stocks, and we can explain what these terms mean based on the framework outlined above.
Growth: targets the Young Growth and High Growth stages—the investment is based on the company’s future trajectory, expected revenue, and profits.
Quality: Targets companies in the High Growth or Mature Growth stages. The company is well-established, as are its competitors; it has one or more moats and is poised for significant future growth.
Dividend: This strategy targets the Mature, Stable, and Decline stages, where the company generates cash but lacks opportunities for reinvestment. It chooses to return this cash to shareholders in the form of dividends or share buybacks. This category notably includes so-called “cannibal” companies, as their stock price is driven upward primarily by share buybacks.
Value: Does not target a specific stage but rather a discrepancy between price and value, regardless of the stage. A company can be classified as a “value” stock at any stage of its life cycle. Generally, there is an underlying issue, or the market perceives it that way.
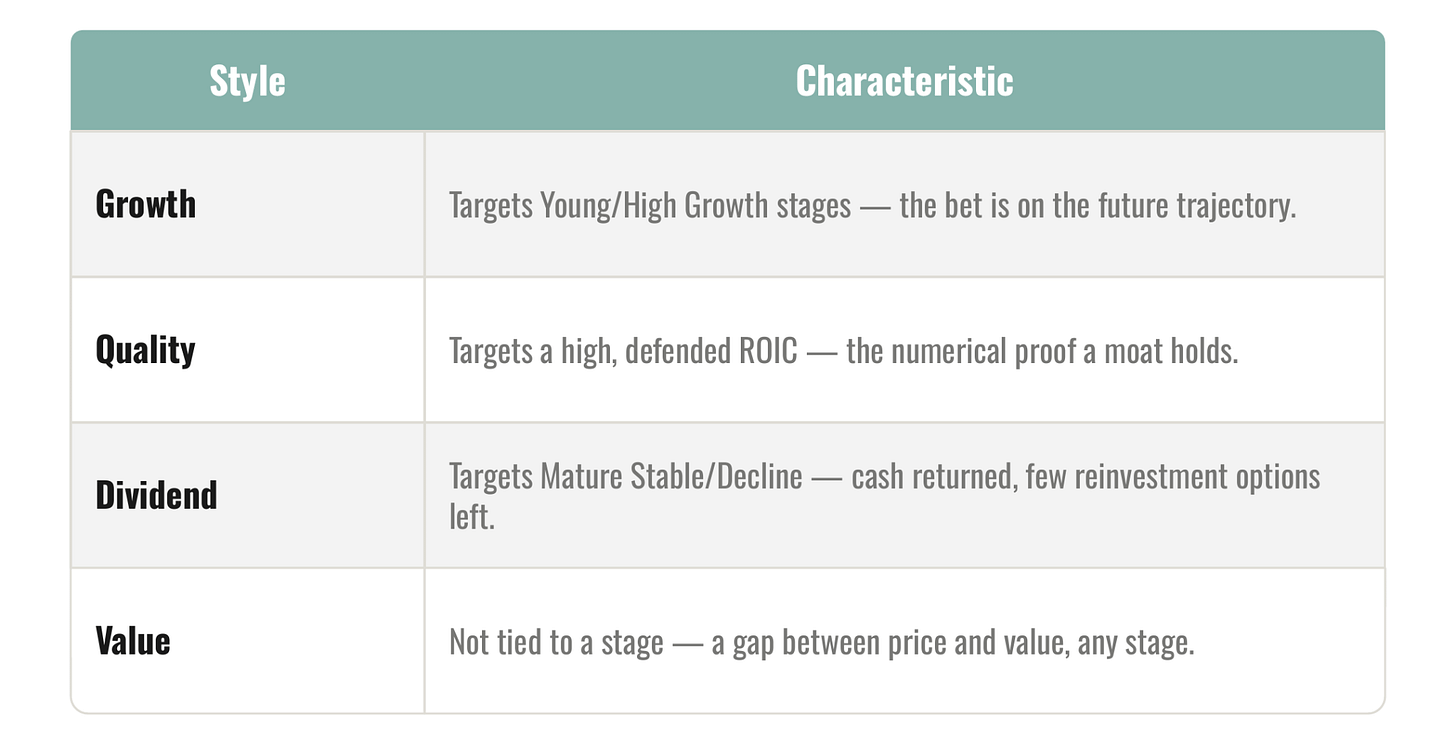
This is a simplified explanation: when you look at the details, a company may share characteristics of several different investment styles. Similarly, there are several investment styles, and they can coexist within the same market.
Beginner investors tend to turn to dividend-paying stocks for their safety and the almost magical appeal of receiving regular dividends. However, the lack of business growth and opportunities for reinvestment often leads to low returns that underperform the benchmark index.
They will also tend to gravitate toward value stocks, thinking they’re getting a good deal (“Company X has a P/E ratio of 5, while its competitors have a P/E ratio of 15—I’m getting a great deal”). In most cases, the reason is valid and stems primarily from issues related to the company’s business or future prospects.
Growth stocks are also very popular because, even though most of them will underperform the index and carry risk, a handful of winners offer the prospect of multiplying your investment in just a few years.
Ultimately, quality stocks will offer the best risk-return ratio due to their competitive moat and long-term growth prospects. As a result, they often command higher prices than other stocks. As with value stocks, the right time to invest is when the company appears (the word “appears” is important) to be facing temporary difficulties.
For educational purposes, I believe the best choice of three stocks to start with is “quality” stocks, given their long-term potential, financial stability, and competitive advantage.
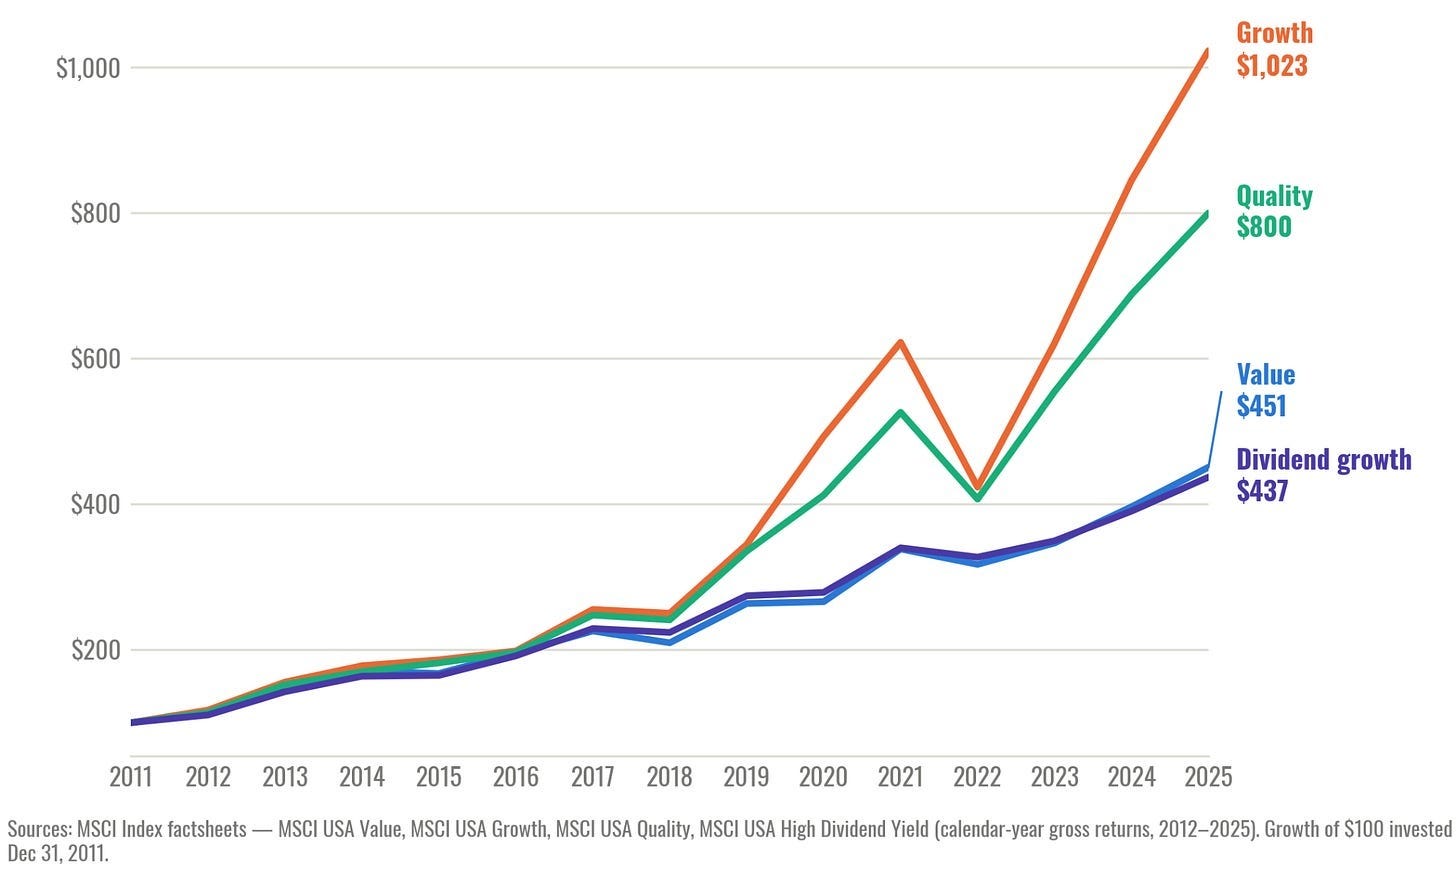
Due to data quality limitations, I can provide a performance breakdown covering the past 15 years, but not beyond that. We have been in a nearly continuous bull market since then, with the exception of dips in 2018, 2020, and 2022.
3.3 Investment Factors
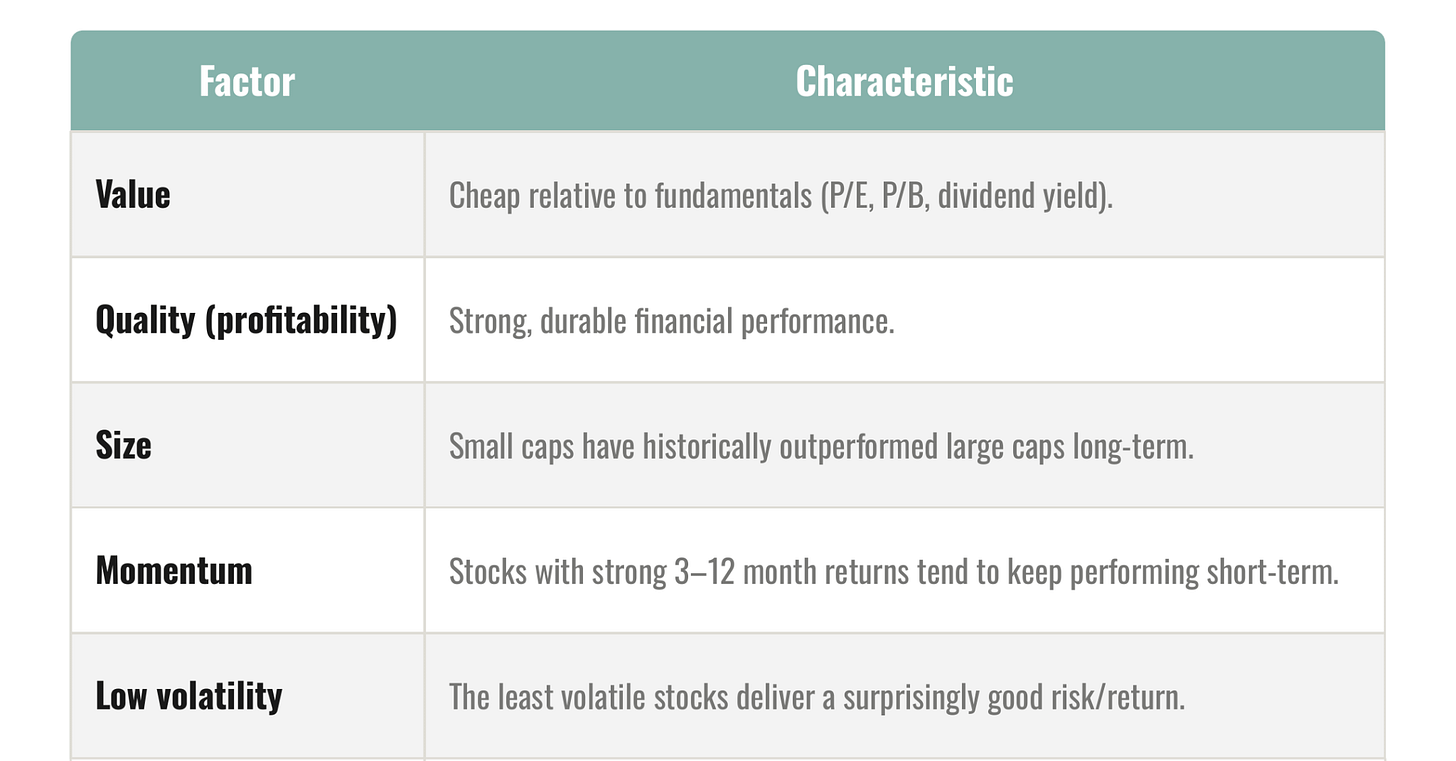
Investment styles can be cross-referenced with factors, which incorporate this classification and add several points:
Size (small-cap stocks have historically outperformed large-cap stocks over the long term). Stocks are classified as small-cap when their market capitalization is between $300 million and $2 billion, mid-cap between 2 and 10 billion, and large-cap above that.
Momentum (stocks that have performed well over the past 3 to 12 months tend to continue doing so in the short term). This reflects a well-known investor bias: investors tend to buy what’s rising and sell what’s falling.
Low volatility (the least volatile stocks offer a surprisingly good risk-return profile, contrary to intuition),
Aswath Damodaran wrote, “A good valuation is a bridge between stories and numbers.” We will therefore move back and forth between the qualitative aspect—part of which we have already presented—and the quantitative aspect, more prominent in the “Financials” section. By cross-referencing the data from the first and second parts, we will provide an overview of the company’s current situation, before exploring its future in a third part.
Part 2 - Financials and Management
Analyzing financial statements is, on the one hand, very straightforward, as one can focus on a few key indicators and obtain initial results that are both robust and compelling. This is also the area where finance professionals have the most data readily available and the greatest ability to interpret it using relevant analytical frameworks.
Gaining an advantage over them in this area is very complex and requires in-depth work. In a future article, I’ll discuss how, despite the excellent candidates who choose a career in finance, individual investors have undeniable advantages. Stay tuned.
One of the key advantages of investing in the stock market is the equal access to information shared with all market participants—namely, public information. To form your own opinion about a company, you have access to the same documents at virtually the same time, and insiders who possess an informational advantage are required to disclose their stock purchases and sales. You’re therefore on a level playing field with other investors and can buy and sell shares in some of the world’s best companies, often for less than $1,000, with trading available nearly 40 hours a week.
So the battle is being fought in the financial documents, which we’ll look at right now.
The three financial statements
Any company listed on an index must follow a number of disclosure rules specific to its listing. In the United States, companies typically publish an annual report called a 10-K and quarterly reports called 10-Qs, which are available on the SEC’s website (the U.S. securities regulator) or on the companies’ own websites (under the “Investor Relations” section). In addition, companies hold earnings calls—presentations of their results that include a question-and-answer session with analysts—and transcripts of these calls are typically made available afterward.
For the rest of the world, the principle is generally the same. Keep in mind that some companies publish their results only in their own language, which makes them difficult for international investors to understand, or they publish their results on a semi-annual basis. This means that any bad news arrives several months later, which amplifies the market reaction, especially given the long-term outlook.
The three financial statements are the income statement, the balance sheet, and the cash flow statement. Accounting standards exist; the main ones are Generally Accepted Accounting Principles (GAAP) in the U.S. and International Financial Reporting Standards (IFRS) in the rest of the world. IFRS is based on GAAP, with some differences between the two.
I’m keeping this brief on purpose; there’s a lot to say about these topics—enough to fill years of study.
The Income Statement
The income statement is a report that shows how the company generated profit from its operations over a given period. It all starts with revenue, from which costs are subtracted to arrive at operating income—a numerical measure that indicates the extent to which the company is generating profit from its operations. After deducting financial and extraordinary items, we arrive at net income, which measures the amount of money available to shareholders.
The key items to look at are:
Revenue
Gross Margin and Operating Margin
Net margin (if I have $1 in revenue, how much profit do I make?)
Financial and Non-Recurring Items
Net income
Here is an example from Booking’s 10-Q for the period ending June 30, 2026.
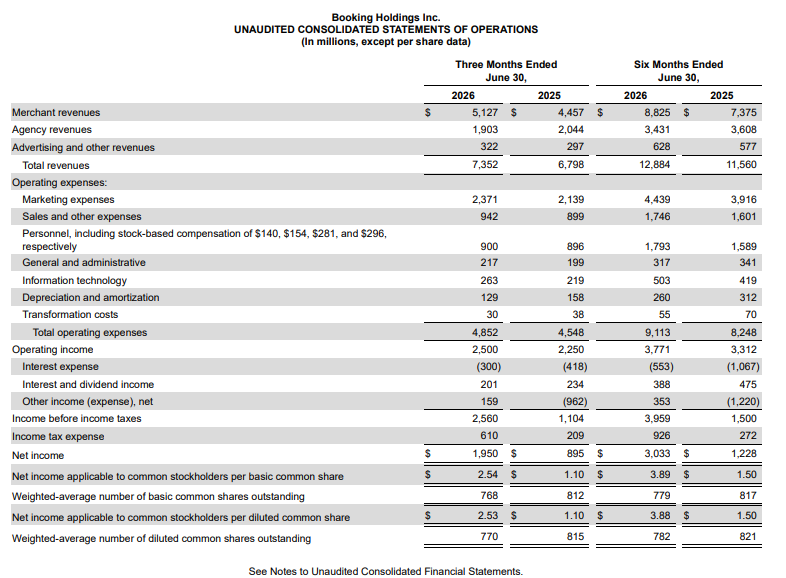
Depending on the business, some companies handle very high volumes with very low margins (e.g., retailers like Walmart or Aldi), while others handle low volumes with high margins (e.g., service or luxury companies). It all depends on the industry and the company’s competitive advantage. It doesn’t make sense to compare different industries directly.
Generally speaking, investors view an increase in margins as a sign of a stronger competitive advantage—and therefore as excellent news. This remains a general rule; the specifics should be examined on a case-by-case basis, depending on the context.
The Balance sheet
If the income statement is a movie, the balance sheet is a snapshot. It shows the company’s assets (and net worth) and how they are financed. The sharpest minds will have noticed that the balance sheet is… balanced: assets always equal liabilities.
A distinction is made between assets (items to be financed) and liabilities, which represent the source of financing.
These assets and liabilities can also be either current—with a useful life of less than one year—or noncurrent—with a useful life of more than one year.
This leaves us with four line items on the balance sheet, as shown in the image below:
The key components are primarily found in the fixed assets. Peter Lynch, the famous investor, has said that he considers current assets to balance each other out, so that only the fixed assets need be considered—whether purists like it or not.
Here is an example from Booking’s 10-Q for the period ending June 30, 2026.
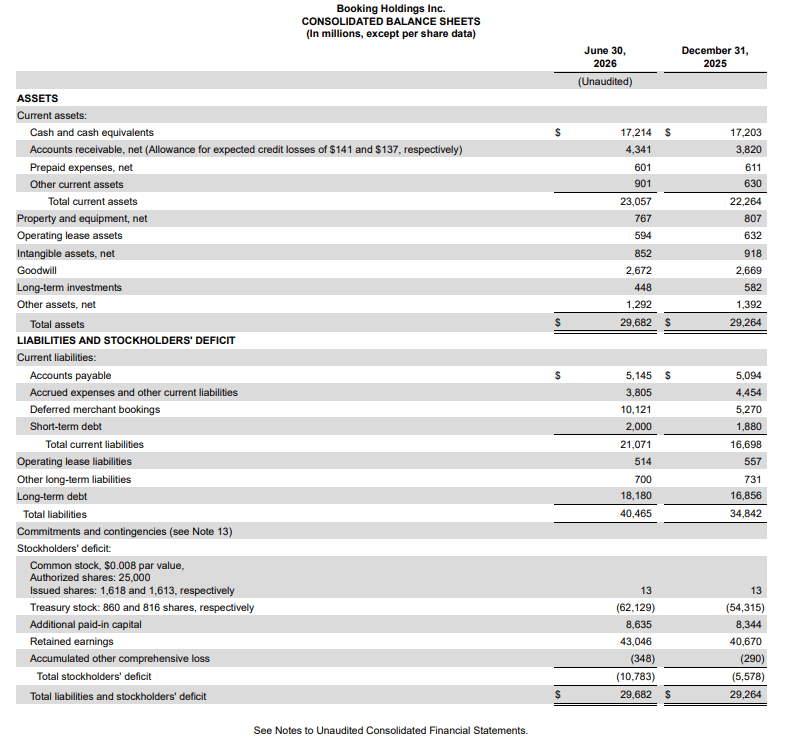
The key items to look at are:
Inventory levels
Cash and cash equivalents
The ratio of long-term debt to equity
The number of shares
But if I had to choose just one, it would be the debt-to-equity ratio (= (long-term debt - cash and cash equivalents) / shareholders’ equity).
Peter Lynch also noted that a healthy debt-to-equity ratio could be as high as 50 percent. Beyond that, in the event of an economic downturn, the company would be exposed to a spiral of debt that could lead to bankruptcy or the dilution of existing shareholders.
You’ll notice that in the example, Booking has negative equity. This is the result of share buybacks carried out year after year. It’s not a problem—neither from an accounting nor a business perspective—and sometimes occurs among large-cap companies that have conducted a significant number of share buybacks.
Another key factor is the change in the number of shares. Most Quality companies will buy back shares, either to reduce the number of shares outstanding or to pay a dividend. Share buybacks offer several advantages:
It is a sign of confidence in the future of management
Fewer shares can cause the price to rise more easily (or fall). In 2021, Xavier Gabaix (Harvard) and Ralph Koijen (University of Chicago) published “In Search of the Origins of Financial Fluctuations : The Inelastic Markets Hypothesis” — one of the most consequential papers in modern finance. Their central finding : financial markets are far less elastic than classical theory assumes. In equity markets, $1 of net inflow moves total market capitalisation by approximately $5.
The tax treatment of share buybacks (capital gains) is generally more favorable than that of dividends. And as long as you don’t sell, there is no tax.
Growth companies have much greater capital needs and typically issue new shares, a process known as dilution. If you’re diluted by 4%, that amounts to a 4% loss on your investment. However, these new funds will enable the company to grow—presumably by more than the amount of that dilution. This is a very strong implicit assumption in growth investing. It isn’t necessarily a bad calculation for the best companies, but dilution raises the bar that your investment must clear to achieve the expected return.
The Cash Flow Statement
This last document is very interesting because it shows us where the cash is going. The table starts with net income and breaks down cash flow into three categories:
Operational Workflows
Investment Flows
Funding Flows
Similarly, here is another example from Booking in its 10-Q for the period ending June 30, 2026.
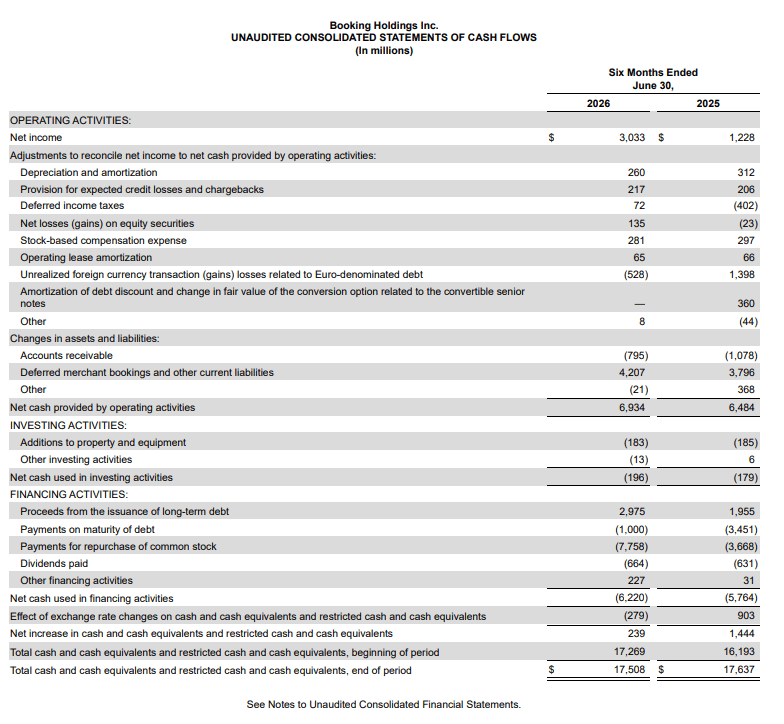
The key items to look at are:
What is the difference between free cash flow (FCF) and net income?
How many years of operating income would it take to pay off the debt?
How many share buybacks or dividends are made?
What are the amounts of stock-based compensation?
Based on the data in the financial statements, we calculate an extremely useful metric: free cash flow (FCF). It is calculated by subtracting capital expenditures (CapEx) from operating cash flow (Cash Flow from Operations).
It answers the question: “How much cash is actually left in the coffers to pay off the debt or pay dividends?”
FCF is a more accurate measure of a company’s ability to create value, unlike net income, which can be manipulated more easily through accounting.
It is necessary to identify the differences between the two.
Just as in a police investigation, reading one of the documents provides information, but it is only by cross-referencing all three documents that one can form a comprehensive picture of the financial situation. This statement can, in fact, be extended to our entire study of quantitative and qualitative factors.
All three documents contain numerous footnotes explaining how the data is calculated in cases where questions about accounting treatment may arise. They often include all sorts of subtleties intended to make the situation appear more favorable. The devil is in the details—in this case, the accounting details.
We mentioned Aswath Damodaran in the previous episode. Here is an overview of the key financial items and expected behavior based on the company’s life cycle for the three types of cash flows.
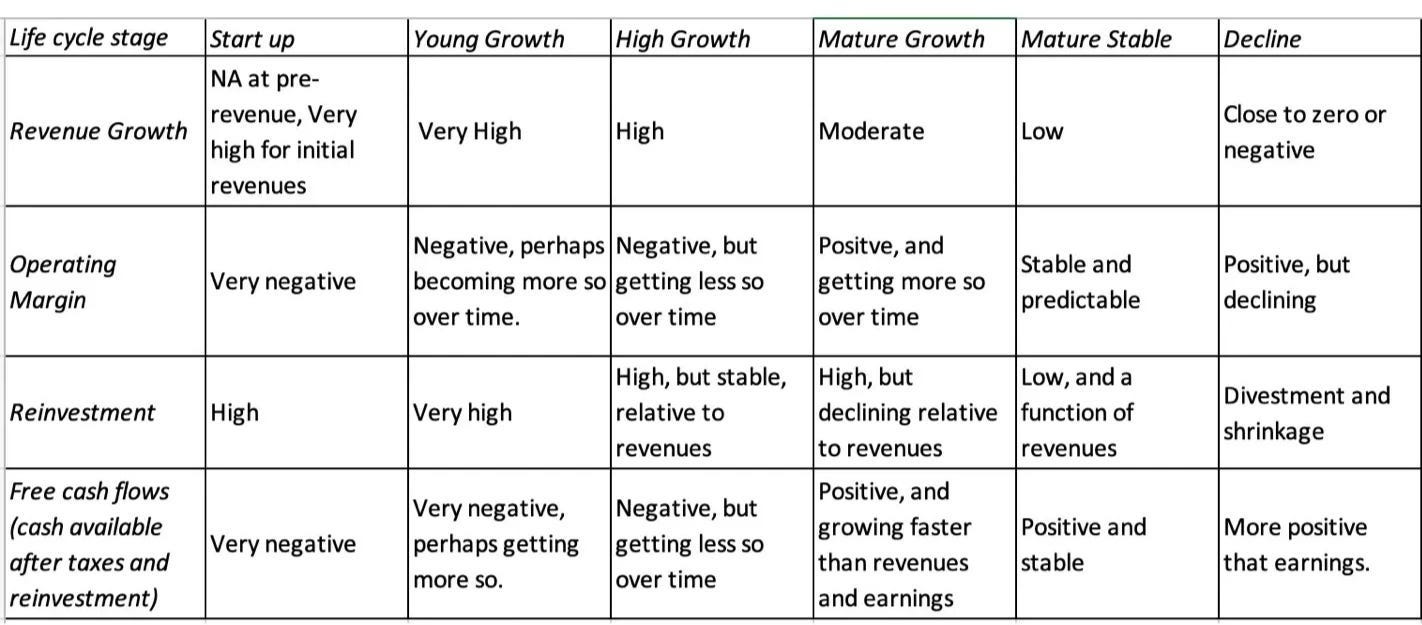
Profitability Ratios
Growth indicators are fairly straightforward: simply compare growth with recent fiscal years, focusing primarily on revenue, margins, and profit (FCF and net income). Profitability indicators are a bit more complex and warrant your attention when cross-referencing the data. In fact, market concerns often center on these points. Therefore, the ability to interpret these figures is essential.
Investment
Here is a non-exhaustive list of profitability metrics, starting with my favorite, ROIC.
ROIC (return on invested capital) :
Formula: NOPAT (operating income after taxes) / invested capital (debt + equity, excluding excess cash)
Purpose: It measures the return generated on the capital actually invested in the business—including debt and equity—but not cash.
Meaning: If a company invests $1 through debt or equity, with a ROIC of 20%, its investment generates $0.20 in operating income after taxes (as long as the ROIC remains at that level). A ROIC higher than the WACC (weighted average cost of capital) is profitable.
Comments: ROIC can be misleading for companies that engage in aggressive asset write-downs or share buybacks.
There is also a variant called ROCE.
ROCE (return on capital employed)
Formula: EBIT (operating income before tax) / capital employed (equity + total debt). This includes any excess cash.
Purpose: It measures the return generated for each euro of capital used.
Meaning: If a company invests $1 in capital (debt + equity), with a ROCE of 20%, it generates $0.20 in operating income before taxes (as long as the ROCE remains at that level).
Comments: Does not take into account non-operating cash flows (such as inventory value, which is important for oil and mining companies). Asset impairments automatically push ROCE higher. Misleading for companies with large amounts of cash.
ROE (return on equity) :
Formula: net income / shareholders’ equity
Purpose: Measures the return generated for the shareholder on the capital they have contributed,
Meaning: If a shareholder invests $1, with a ROE of 20%, this generates €0.2 in profit for the company.
Comments: It may be artificially inflated by high leverage or by low equity (aggressive—or even negative—share buybacks).
These three indicators should be analyzed in conjunction to assess the quality of the business and its management. It is helpful to compare these three metrics for the company with those of its competitors. Note that this is more difficult for companies with several completely different business lines, such as Amazon, which combines retail operations with data center operations.
There’s also ROA, which I don’t use very often:
ROA (Return on Assets) :
Formula: net income / total assets
Purpose: Partially corrects the bias in ROE by including debt in the denominator—less sensitive to leverage, more appropriate for comparing companies with different capital structures
Meaning: If the company generates $0.20 in net income for every $1 of total assets, its ROA is 20%.
Comments: This metric is less precise than ROIC/ROCE when measuring pure operational efficiency, since total assets also include non-operating assets (cash, equity investments) that ROIC specifically excludes. Furthermore, net income needs to be examined to determine whether it provides an accurate picture of reality.
Here is a summary of the four indicators:
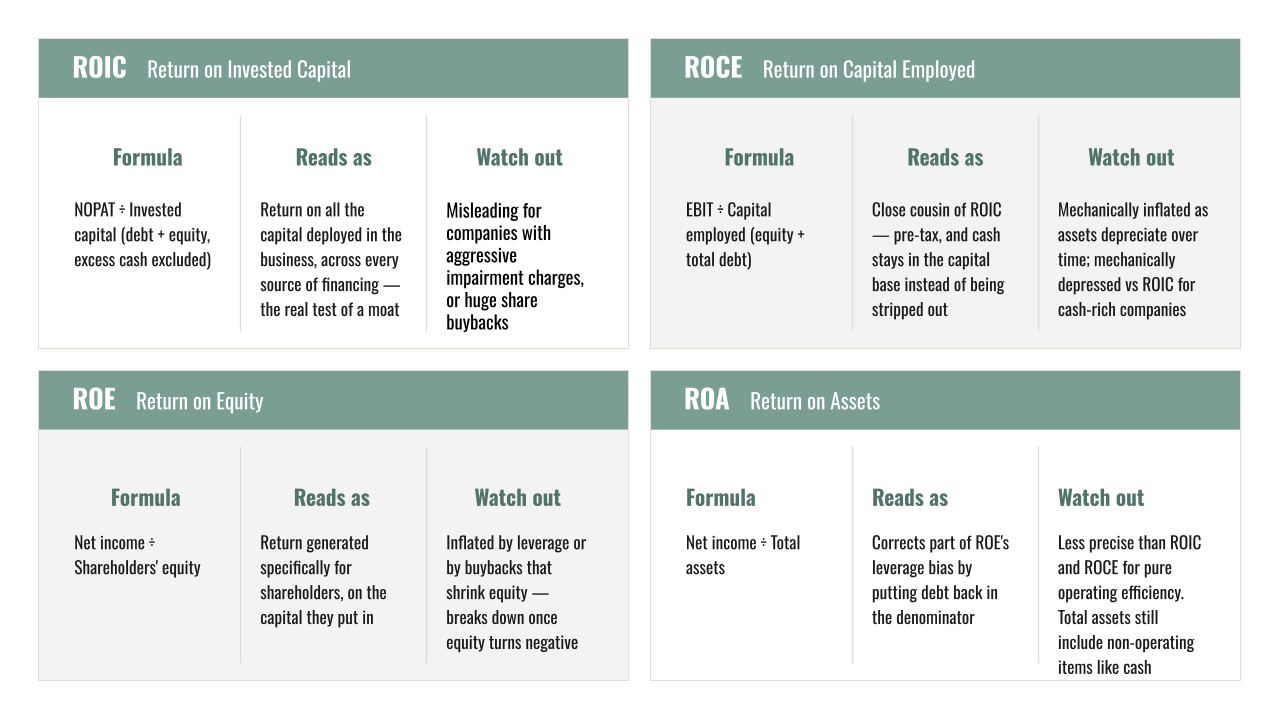
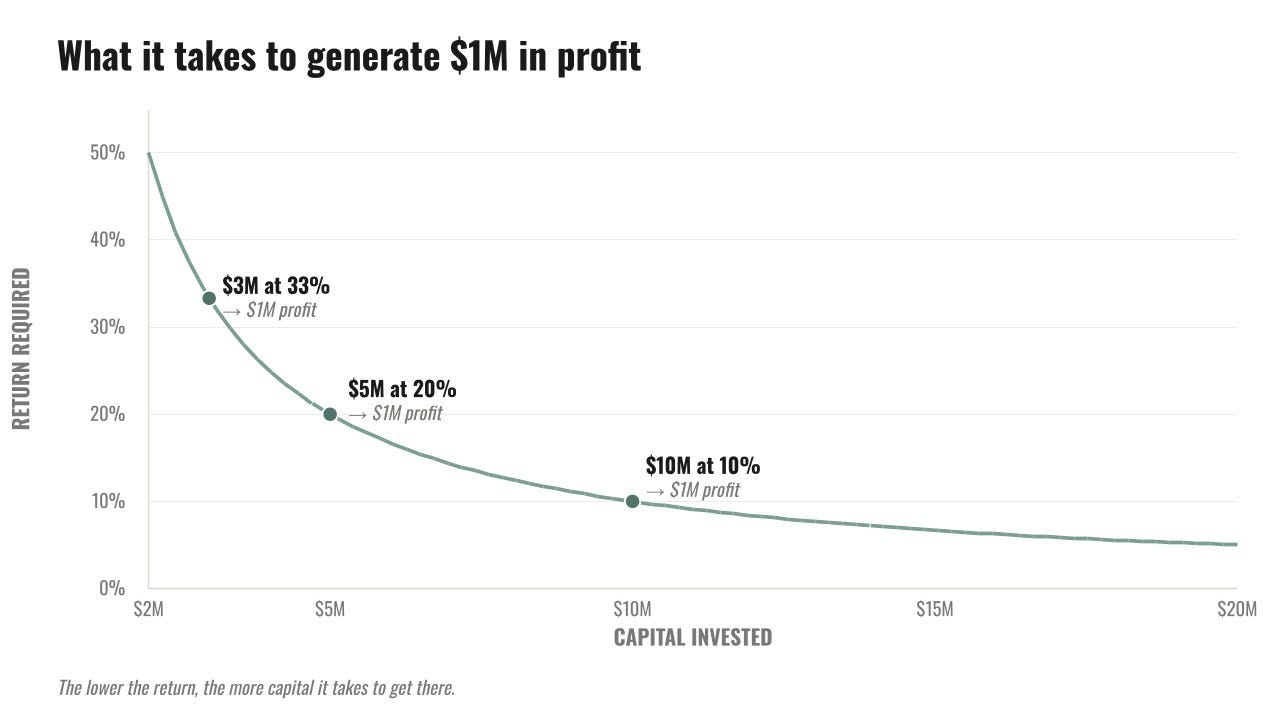
Also note that it is necessary to evaluate investment opportunities and weigh them against profitability: To generate $1 million (in NOPAT), for example, one could:
Invest $10 million at 10%,
Invest $5 million at 20%,
Invest $3 million at a 33% rate.
A company will be able to continue investing as long as its resources allow, depending on its market and the creativity of its management.
Net Margins
There are two key indicators for margins.
Net margin:
Formula: net income / revenue
Profit: what actually remains for shareholders from every dollar of revenue, after all expenses have been deducted,
Meaning: If the company generates $1 in revenue with a net margin of 20%, $0.20 in net income remains for shareholders (as long as the net margin remains at that level),
Notes: Distortion may occur if the company has subsidiaries in which it owns between 50% and 100% of the shares—in which case, minority interest must be adjusted.
FCF margin :
Formula: free cash flow / revenue
Usefulness: How much of every dollar in revenue actually remains as cash after capex is deducted,
Meaning: If the company generates $1 in revenue with a 20% FCF margin, it converts $0.2 of that revenue into actual available cash (as long as the FCF margin remains at that level),
Notes: There may be some distortions, particularly if a company sells subscription-based services: only the portion that has already been completed and billed is recognized, not the entire plan.
It is important to compare and analyze the differences between net income and free cash flow—and thus between their margins. This is a useful exercise to perform during your analysis to gain a thorough understanding of specific accounting practices.
A few other metrics that I don’t use:
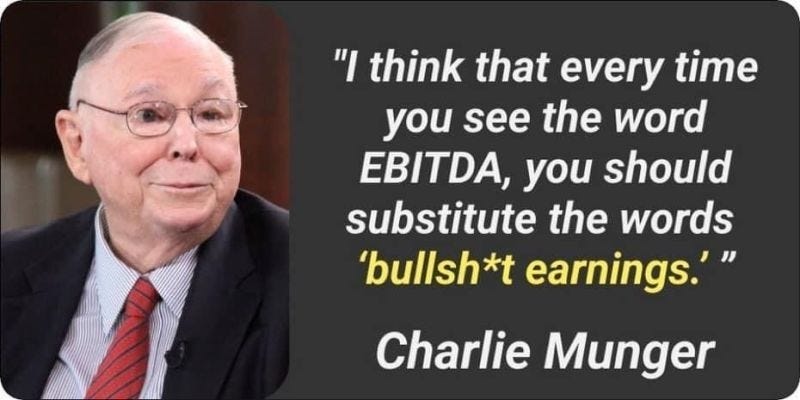
EBITDA: Earnings Before Interest, Taxes, Depreciation, and Amortization. This metric omits too many important factors to provide an accurate picture of the business’s profitability. Charlie Munger had a famous remark on this subject:
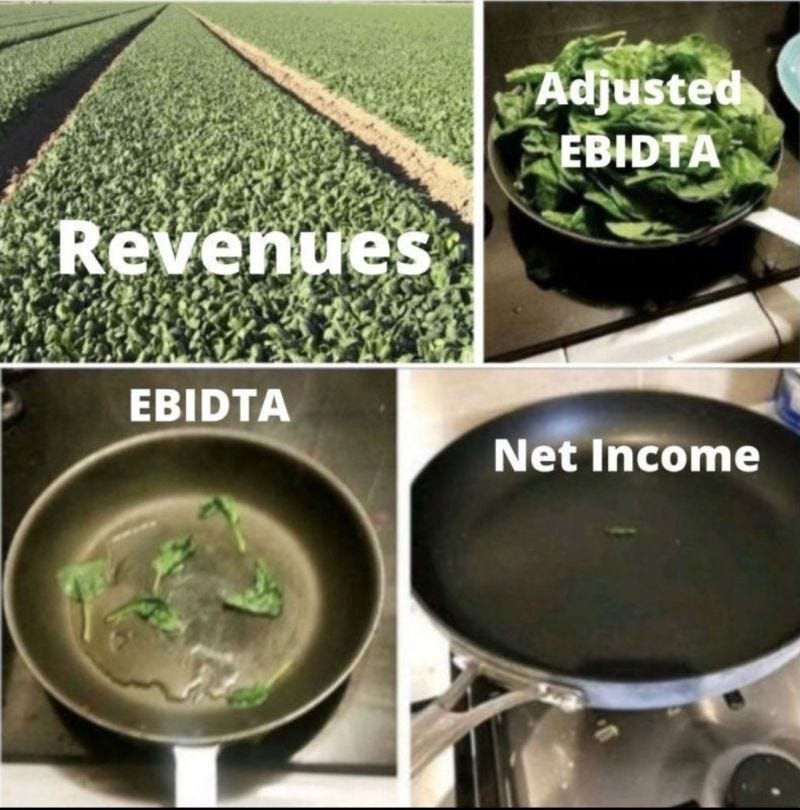
Worse still, some companies prefer to report adjusted EBITDA.
A word of advice: Use the figures reported in accordance with accounting standards as your point of reference. Generally, those who present you with adjusted or non-GAAP figures do so to paint a rosier picture of reality—in other words, to make a sales pitch—rather than to tell the truth.
Every rule has its exception: I recently saw a presentation of results from Novo Nordisk that showed sales figures adjusted for two factors: one was a reversal of an accounting provision (a valid reason), and the other was due to an impairment charge related to discontinued drugs (a debatable reason). I’ll leave you with the image below, which pretty much sums up my opinion on the matter:
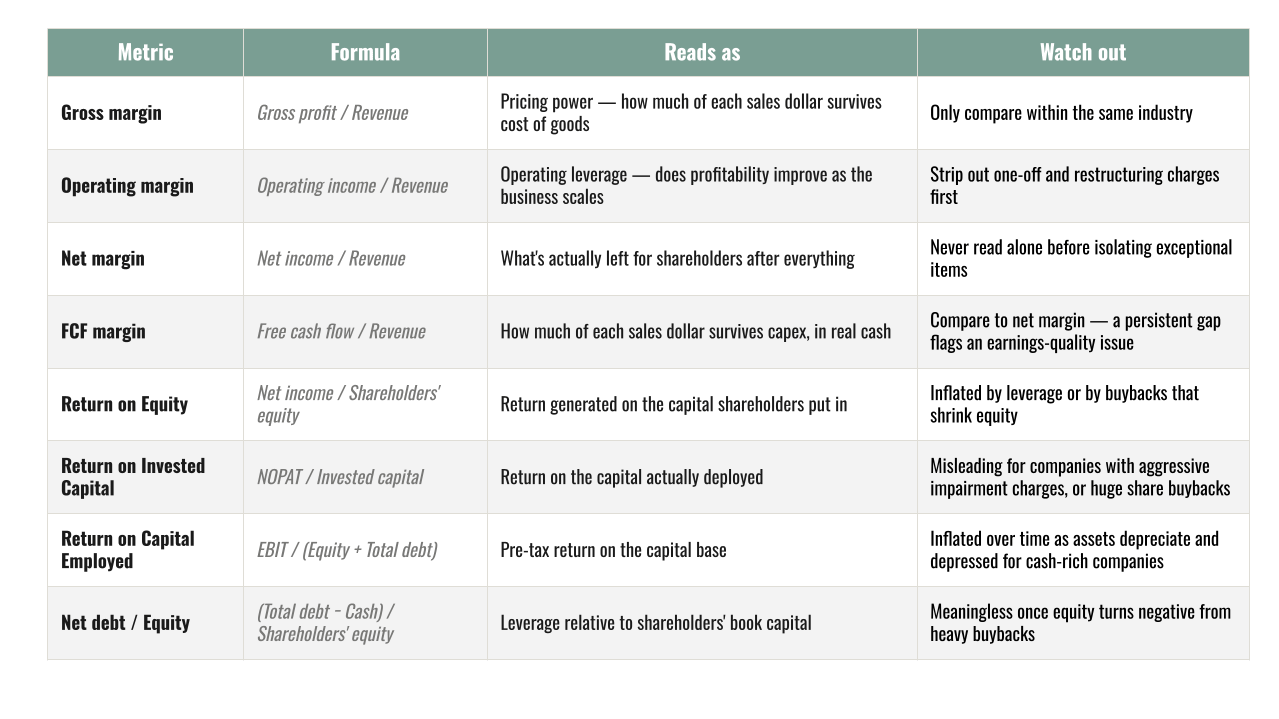
Here is a summary of the key profitability metrics:
3. Management
There is a fundamental problem between shareholders and managers: the manager might seek to line his own pockets with shareholders’ money instead of acting as a good steward. This has been theorized by several well-known authors.
The renowned Adam Smith had already pointed out in *The Wealth of Nations*:
The directors of such companies, being the managers rather of other people’s money than of their own, it cannot well be expected that they should watch over it with the same anxious vigilance with which the partners in a private copartnery frequently watch over their own.
In 1976, a seminal article by Michael Jensen and William Meckling (“Theory of the Firm: Managerial Behavior, Agency Costs, and Ownership Structure,” Journal of Financial Economics) defined agency theory, a famous milestone in the history of management.
They define the agency relationship as a contract under which the principal (the shareholder) delegates decision-making authority to an agent (the manager), and argue that if both parties seek to maximize their own utility, there are good reasons to believe that the agent will not always act in the principal’s best interest. It was this article that gave rise to the term “agency costs”—the cost of this conflict of interest.
The goal of this entire section will therefore be to answer the following questions:
Who are these managers?
Are they effective?
Can I trust them with my money?
The order of the questions is designed for educational purposes. When analyzing actions, you will inevitably ask yourself all three questions at the same time.
To assess the management team, simply asking your favorite AI a question, reviewing the financial documents, and taking a look at LinkedIn should provide you with all the information you need.
Management Effectiveness
Based on my studies in management and my experience as a project management professional, the theoretical definition of a good manager is based on performance indicators and their ability to meet them. It is very difficult to distinguish a good manager from a favorable situation. This point is essential: a good manager is often considered as such because they are successful.
The challenge here will be to distinguish between economic conditions and the manager’s performance.
One way to do this is to examine the track record—that is, actual performance versus promises—and thus compare the set goals with the actual results using the financial statements from recent fiscal years.
The renowned Warren Buffett wrote in his 1979 letter to shareholders:
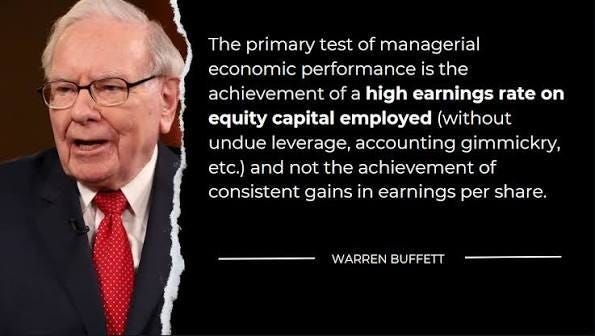
You’ll notice the characteristic AI style of “it’s A, not B”—nearly 50 years ahead of its time. A pioneer.
In practical terms, this quote means that you can significantly increase your profits by investing heavily, even with a low rate of return. It’s like saying that to double your savings, you can either double your existing capital through your investments or contribute the same amount from your savings.
True management competence is measured by the return on capital already invested.
Ideally, then, you’ll want: excellent management capable of generating very strong returns on invested capital, along with the reinvestment opportunities inherent in the business. Ideally, you’ll want plenty of both if you’re taking a long-term view.
Its management ability is measured by capital allocation, which varies depending on the stage of the life cycle:
First and foremost, a company will finance its organic growth through items such as capital expenditures, R&D, and working capital needs. This is the best use of capital as long as the return on that reinvestment exceeds the cost of capital. As the company grows, these opportunities diminish over time. In economics, this is known as the law of diminishing returns.
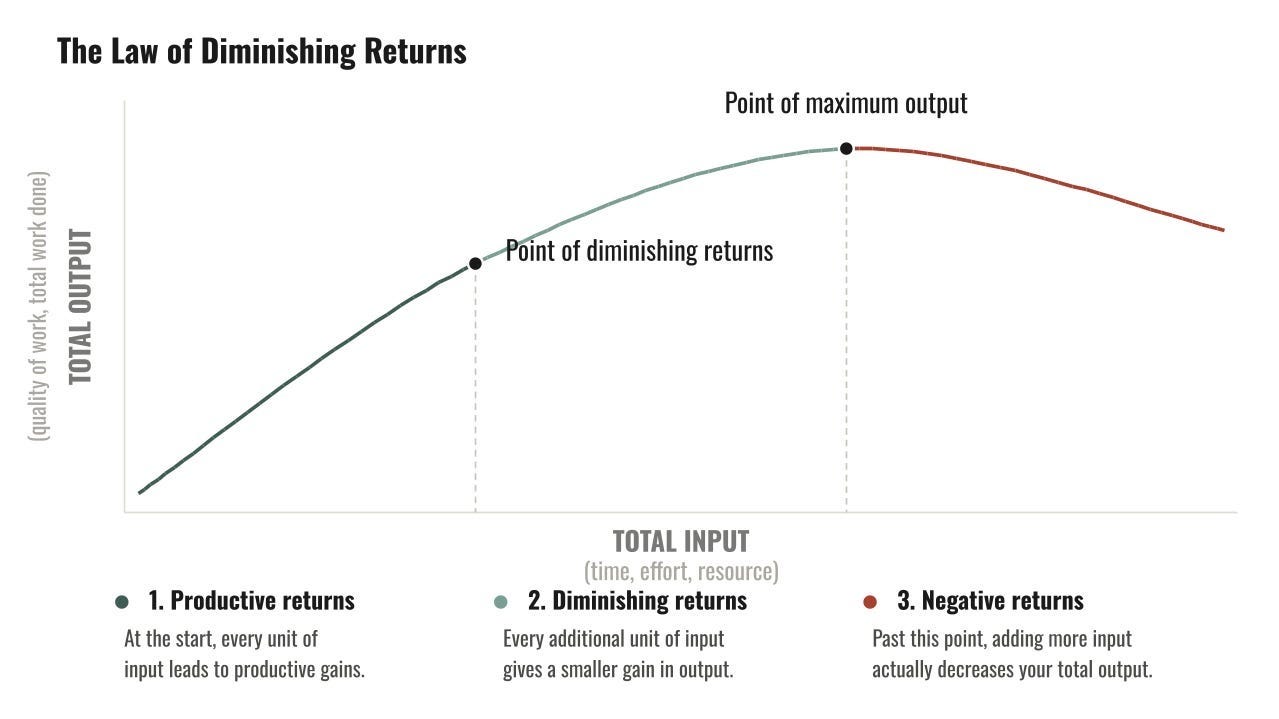
If there is capital remaining beyond what organic growth can absorb at a good rate of return, three options are available: external growth (M&A), dividends, or share buybacks. Be careful, though: external growth is generally a bad bet for shareholders. Personally, I prefer to avoid share buybacks, which are often based on overly optimistic assumptions and coincide with market highs.
Management is expected to return to shareholders any funds that cannot be invested with a sufficient rate of return.
If you invest in dividend-paying companies, check their ability to pay dividends during difficult times (COVID-19 in 2020, the Global Financial Crisis in 2008, etc.).
Also keep in mind that, in a young company, good management is the source of competitive advantage, and that advantage will grow over time. Poor management—or management grappling with structural challenges in its business—will see its competitive moat erode and, consequently, its profitability decline.
Trust
The best way to earn management’s trust is to make sure your interests are aligned with theirs.
Nassim Nicholas Taleb in his 2018 book, Skin in the Game: Hidden Asymmetries in Daily Life, describes a concept that has since been widely cited: “Skin in the Game.”
If the manager holds a significant—or even a majority—stake in the company where you’ve invested, your interests are aligned because he shares your goal: to drive up the stock price and thereby maximize your wealth.
We will therefore prioritize seeking out founding executives, who have the advantage of holding a significant stake in the company and possessing a long-term vision. The superior performance of owner-operators has been proven over the long term, due to the natural selection that occurs over time between founders who are excellent managers and those who stagnate or go bankrupt.
When it comes to CEOs who are not founders, it is important to review their compensation plan in particular: Is it in cash? In stock? What performance goals is it tied to?
By choosing a founder who runs the company, you stack the odds in your favor, but it doesn’t guarantee success. I experienced this firsthand as a counterexample when I invested in a promising Italian consulting firm. For several reasons, I sold my position two years ago, one month before the bombshell in September 2024: The press reported that the founder and CEO of Digital Value, Massimo Rossi—founder, CEO, and largest shareholder of Digital Value (an Italian IT company listed on the Milan Stock Exchange)—was arrested on October 16, 2024, for corruption and rigging public bids in the Sogei case (the IT company of the Italian Ministry of Economy). He resigned that same day, and the stock price plummeted during the trading session. In less than a month, the stock plummeted by 80%. It was delisted a few months ago.
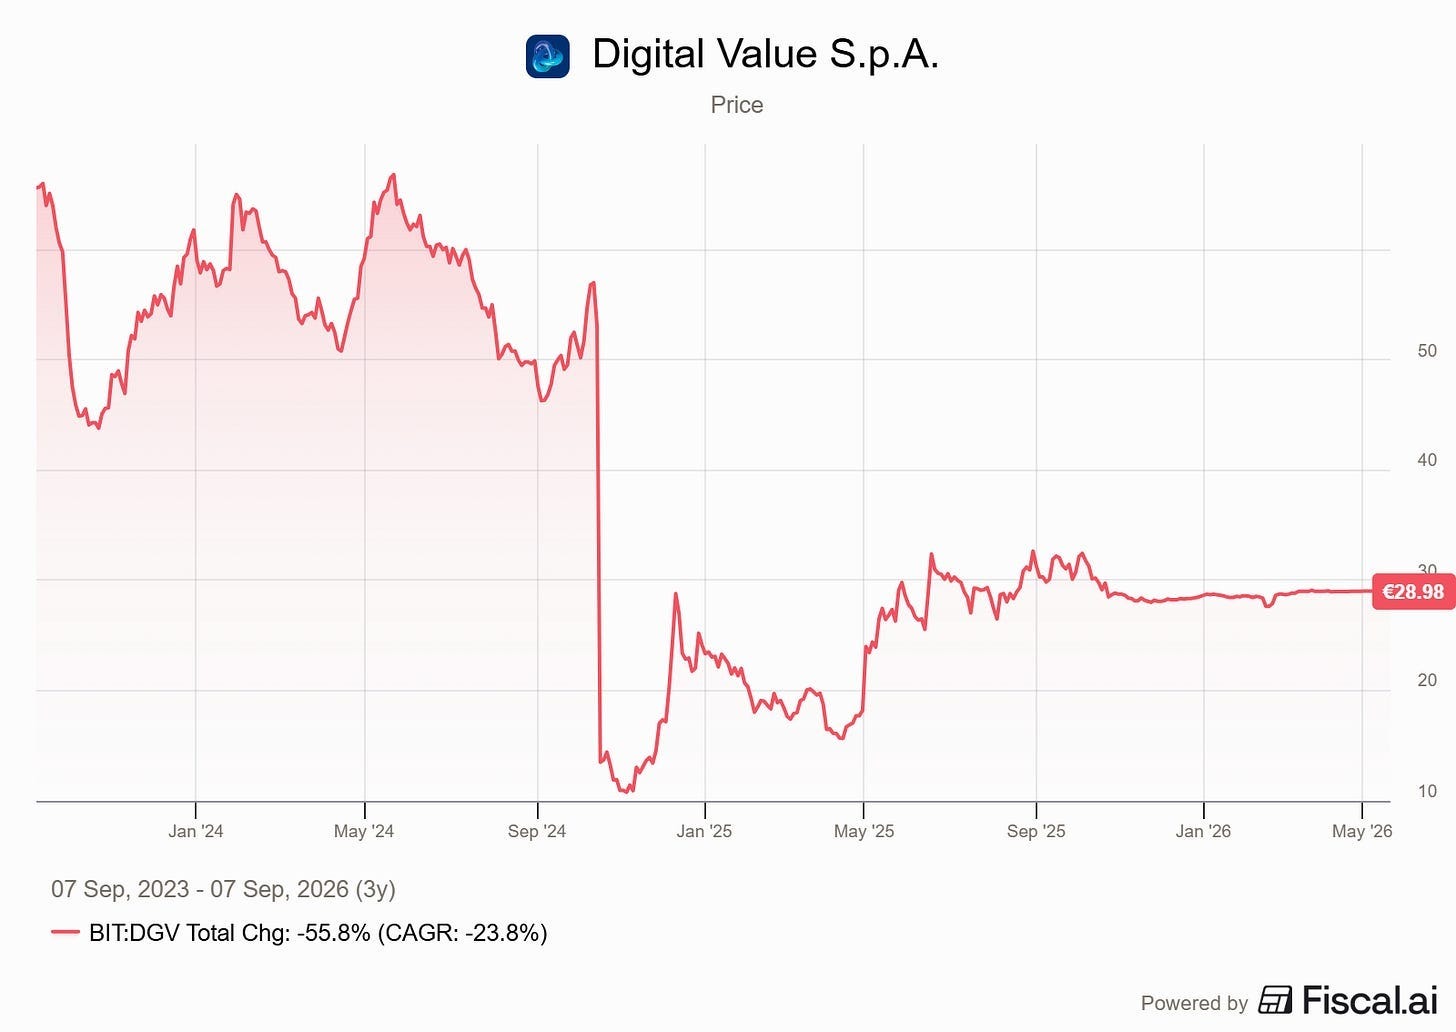
The executive had previously been praised for his management skills and vision. This is just one example among many of the risks associated with portfolio concentration and what is known as company-specific risk.
Furthermore, a good place to assess management’s integrity is in the financial statements. I’ve previously discussed metrics that are adjusted to paint a rosier picture than usual, but management under pressure to deliver good numbers may be tempted to shift their perspective. To name a few examples, I’m thinking of recurring non-GAAP restatements from one quarter to the next, changes in accounting estimates (depreciation periods, provisions), aggressive revenue recognition, and “exceptional” expenses that occur too frequently to be truly exceptional.
The devil is in the details—in this case, accounting details.
This section concludes the static analysis of the company and helps address some initial questions regarding the quality of the business and your desire to keep it in your portfolio. The next step will be to look ahead, considering both bullish and bearish scenarios, and to estimate an expected return based on the company’s possible futures.
Part Three - The Outlooks
1. The Two Theses
The goal of this section is to present the facts on both the upside and downside possibilities. This is meant to guard against two well-known pitfalls:
Only considering the upside is wishful thinking, which can cost you dearly in monetary terms.
Only considering the downside is catastrophizing, which can cost you dearly in terms of regret.
Having solid projections about the future will make it much easier to hold positions psychologically, because you’ll always have a rational anchor with arguments to support you or guide your decisions. Doing nothing is also a decision.
Note that if you don’t have the facts to answer the questions below, your investment thesis isn’t solid, and you’re better off moving on and investing in another company or another sector.
The same works for a stock that has risen sharply — in that case, it’s the reverse:
Results above expectations
Guidance raised
Macroeconomic factors
Company-specific catalysts: an influential investor taking a stake, a major contract signing, a technological breakthrough
Next, we look at the bear thesis. It generally builds on the “why did the stock drop” elements, going one level deeper:
Loss of market share to competitors.
Operating margins under pressure (rising costs, falling selling prices).
Excessive debt levels or insufficient cash (cash burn).
An outdated or disrupted business model.
Management changed strategy, and products no longer sell because they no longer address the right needs.
Is this a structural problem or a conjunctural one?
In light of this, we must ask ourselves what evidence supports these fears, and whether they are substantiated:
Analysis of financial statements (balance sheet, income statement),
sector reports,
Comparison with peers.
Supplier and Customer Analysis
To take this line of thinking all the way through, ask yourself the following questions: What if the bear thesis is really true? What does that mean?
The idea is to quantify the impacts described above.
At the end of your argument, you should be able to identify clear criteria that allow you to conclude that the bearish thesis is valid. For example:
Revenue growth of X% or less
Margins under Y%
Competitors’ market share exceeds Z%
Generally speaking, some of the arguments raised are true, but the company will be able to address them easily. Then put yourself in management’s shoes and ask yourself what options they have to remedy the situation. That is the whole point of the bullish thesis.
What specific actions could management take? They can generally:
Launching new products or changing strategy,
Start a price war (very bad in the short term),
Take over a troublesome competitor,
Focus on its core business by selling or divesting segments,
Reduce costs.
Next, check management’s actions and communication
Is management transparent about the difficulties and credible in its solutions? Does management hit its targets from one report to the next? Are they too optimistic?
What actions has management planned to take? Every action in the plan should improve the fundamentals and restore investor confidence.
As with the bear thesis, you should be able to identify indicators that confirm the bull thesis. For example:
Revenue growth above X%
Margins above Y%
The company’s market share above Z%
These actions need to produce concrete results that address the difficulties. So we look for catalysts, which are specific events that trigger a significant movement in a stock’s price, or in the market as a whole.
They come in several types:
Performance catalysts: the company beats expectations.
Market catalysts:
-Index inclusion: which forces thousands of ETFs to now buy the stock.
-Coverage initiation: when an analyst revises their target price
-Short squeeze: an upward market move, or a move above a certain threshold, can force short sellers to urgently buy back their position.Strategic catalysts:
Buyout or merger: an acquisition offer from a major player.
Spin-off: separating a business division to reveal the hidden value of a subsidiary, which then gets sold by funds and ETFs whose underlying holding, however interesting, no longer fits their mandate.
Exclusive partnership: becoming the “preferred” supplier of a market leader.
4. Macroeconomic / regulatory catalysts:
Interest rate pivot: any change in interest rates, particularly US Treasury yields, changes the yardstick against which all investments are compared.
Changes in commodity prices.
The end of a recession, or a price change affecting customers’ budgets.
Regulatory framework changes.
The event happening is one thing, but remember that the market thinks in probabilities. The price adjusts toward the news as the catalyst becomes clearer and clearer — not at the moment it actually occurs.
I also note the blind spots in my research, so I can keep track of unresolved points that may have slipped through the analysis. It’s not possible to answer all of these questions exhaustively — otherwise investing would just be a matter of computing power. Investing requires acting on imperfect information: that means making a decision without knowing everything, but with enough information to act with a good level of confidence.
2. How much?
This section addresses the question of profitability, approached through two methods:
Valuation, which consists of determining the company’s intrinsic value from its own future cash flows, independently of what the market thinks.
Pricing, which consists of determining how much the market is willing to pay for those same flows, through a multiple.
I’m not a finance professor. So I’ll leave it up to you to decide if you’re interested in what Aswath Damodaran—who is one—has to say on the subject. He has plenty of free resources on his Substack, YouTube videos, and books that are excellent reads, particularly his book *The Little Book of Valuation*.
When it comes to valuation, the gold standard is the DCF method, which involves calculating a company’s future cash flows and discounting all of its future cash flows to the present to derive its intrinsic value. This value is independent of the market’s assessment of the company. It is, therefore, an intrinsic valuation method.
Personally, I believe that the information needed to accurately perform a DCF analysis (5- to 10-year growth rate, terminal value, discount rate) cannot be estimated with sufficient reliability for most companies. Having built plenty of projections as a project manager, most initial estimates turn out to be completely wrong — even more so the further out the date, or depending on the quality of your starting assumptions. And having made and seen estimates made, there’s a tendency to land on the number you wanted in the first place. The DCF creates an illusion of expertise based on mathematical and logical reasoning whose foundations are often uncertain.
For this model to be relevant, a suitable company must be predictable, which narrows the range of possibilities.
Pricing, on the other hand, involves valuing the company based on comparables. In this case, you believe that the market is generally reasonable but has misjudged a specific value. It is therefore a relative method, divided into equity multiples and firm multiples.
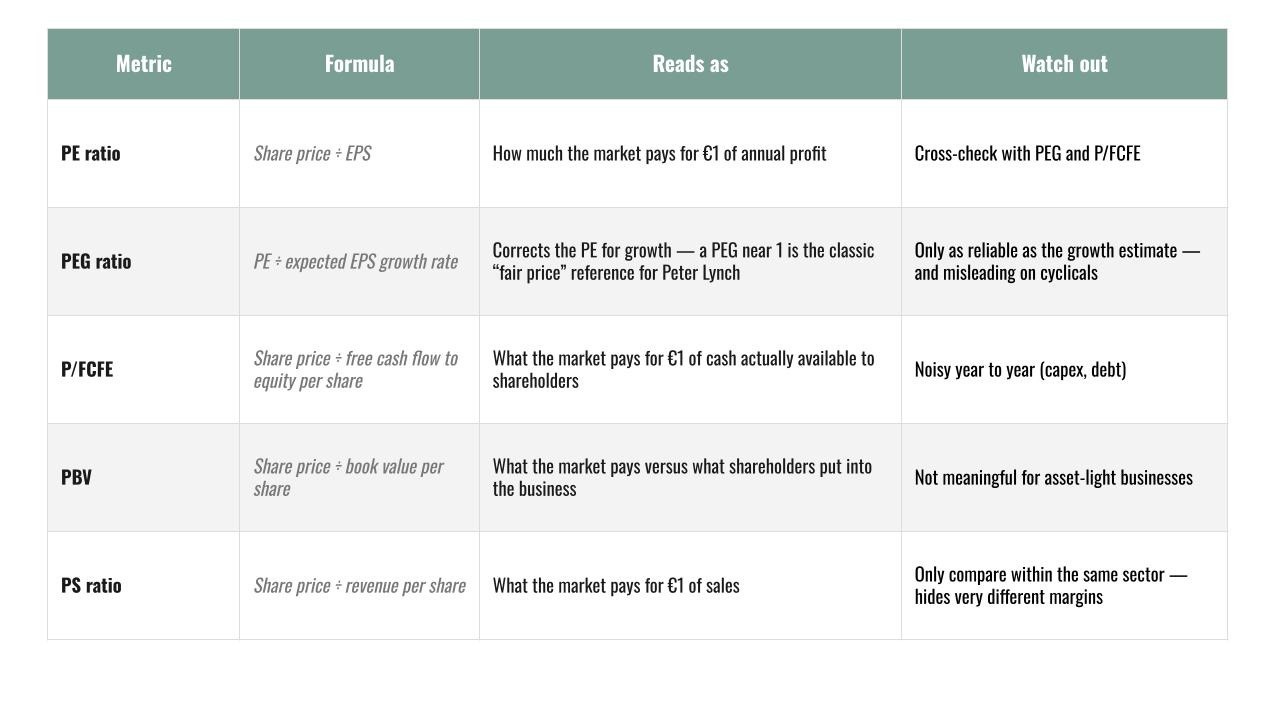
Equity multiples
PE ratio (price/earnings):
Formula: stock price divided by earnings per share —
Meaning: how much the market pays for one euro of annual profit. If a stock trades at 20 times earnings (a P/E of 20), you get back your money with the current earnings in 20 years.
Comments: depends heavily on the company’s growth and risk: you cannot say based on this unique metric that it is cheap or expensive. PE ratio Sensitive to the same accounting distortions as net income covered in the previous article (one-off items, minority interests). Best cross-checked against P/FCFE below, and the PEG ratio.
PEG ratio (PE to growth):
Formula: P/E divided by the expected earnings growth rate — corrects the raw P/E to compare different growth profiles.
Meaning: A P/E of 30 with 30% growth gives a PEG of 1; the same P/E of 30 with only 10% growth gives a PEG of 3. Peter Lynch said that a good PEG ratio is when the growth is equal to the PE (ex: 30% growth EPS with a PE of 30).
Comments: In the case of a cyclical company, the opposite is true. A company’s P/E ratio will drop at the end of a peak (due to investors’ expectations of a decline in the stock price) and will be extremely high at the trough of the cycle,
P/FCFE (price to free cash flow to equity):
Formula: share price divided by free cash flow to equity per share.
Meaning: how much the market pays for one euro of cash actually available to the shareholder.
Comments: In theory, FCF provides a clearer picture of the company. However, significant changes in investment or credit policies will skew the measurement. It should be compared with the P/E ratio.
PBV (price to book value):
Formula: share price divided by book value (equity) per share.
Meaning: how much the market pays relative to what shareholders have contributed or left in the company, on the balance sheet.
Comments: this was the signature formula of the famous investor Benjamin Graham. Since companies now have significant intangible assets (goodwill, brand, software), this key indicator of value investing is used much less frequently.
PS (price to sales):
Formula: share price divided by revenue per share.
Meaning: how much the market pays for one euro of sales —
Comments: the only one of the five ratios that still works even when the company isn’t yet profitable (young, fast-growing companies). Be careful to compare companies in the same sector, as the same revenue multiple can hide very different margins.
Firm multiples
These take into account not just equity, but the full set of long-term resources available, namely equity and debt, minus net cash, to arrive at enterprise value. The advantage is being able to compare companies with different debt ratios by leveling this base.
EV/FCFF (value to free cash flow to firm)
Formula: enterprise value divided by the cash available to all capital providers (debt and equity), before any debt service.
Meaning: how much the market pays for one euro of cash generated by the company and available to all of its capital providers (shareholders and creditors), before any debt service.
Comments: In theory, FCF provides a clearer picture of the company. However, significant changes in investment or credit policies will skew the measurement. It should be compared with the P/E ratio.
EV/EBIT
Formula: enterprise value divided by operating income before interest and taxes
Meaning: measures operating profitability independently of the financing structure (debt vs. equity) and of each country’s tax treatment.
Comments: allows comparison of companies with very different debt levels without distorting the reading, unlike the PE ratio.
VS (value to sales)
Formula: enterprise value divided by revenue: it is the firm-side equivalent of PS.
Meaning: how much the market pays for €1 of sales.
Comments: it still works even when the company isn’t yet profitable (young, fast-growing companies). Be careful to compare companies in the same sector, as the same revenue multiple can hide very different margins.
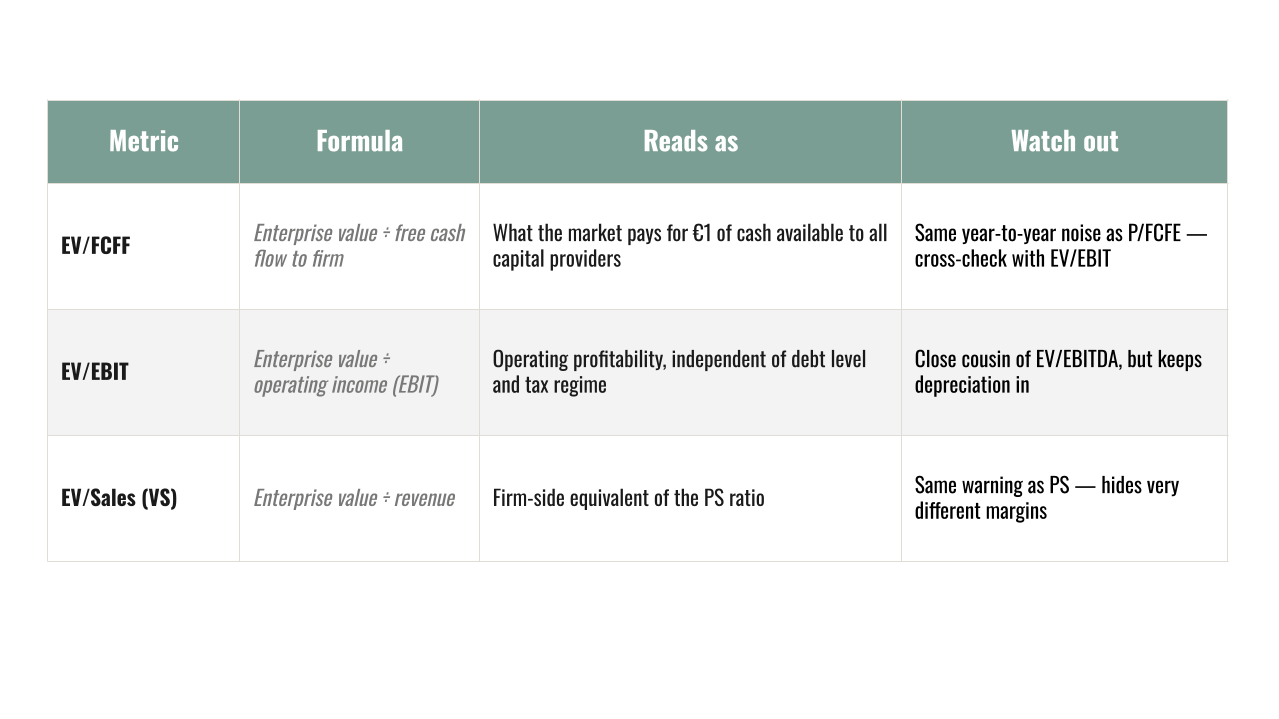
We look for a gap between what the company is worth (as described in the two theses section) and the price we pay for it, with the multiples shown above.
In practice, my method does not involve directly comparing a company to a basket of publicly traded competitors. I prefer to build a matrix of scenarios: estimating the company’s future earnings under various assumptions (bear/base/bull), then cross-referencing them with possible multiples. To make this simple and easy to understand for my readers, I use the P/E ratio after adjusting for non-recurring items.
The idea is to identify a range of possibilities using a pricing scorecard in this format. Then, based on the factors in the bull vs. bear analysis, to determine where my conviction lies.
The goal will be to monitor the company over time and verify that it is on track with my profitability assumptions.
Here’s an example I wrote in one of my articles as part of a deep dive into AppLovin.
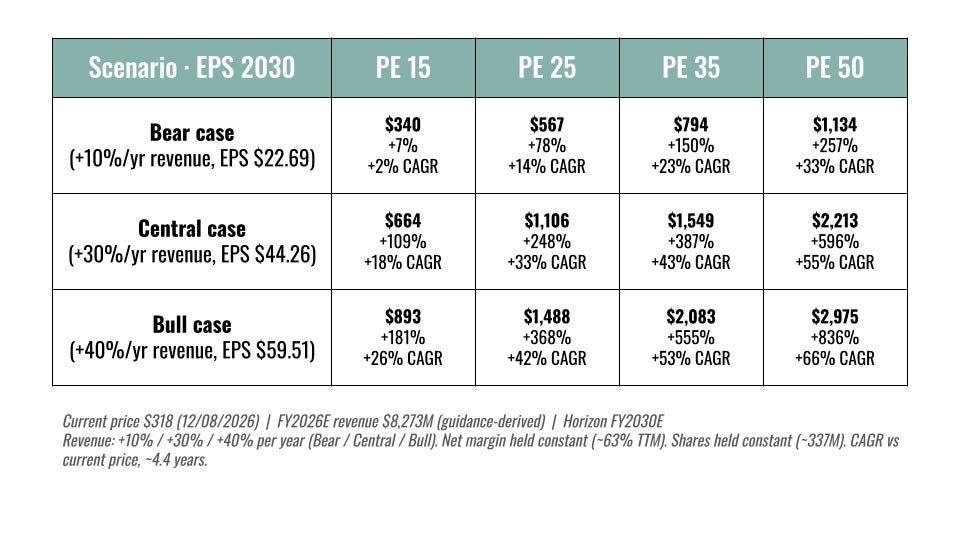
So we’ll be looking for the valuation target a few years down the road, but in the short term, the stock price could react in an irrational way. I’ll break this down into two parts: fundamentals and investor sentiment.
The short-term volatility will prompt further reflection on investor sentiment, which will be the subject of another series of articles. For now, we are in the process of identifying three stocks as part of a pilot phase, as mentioned in the first article of the series.
That’s how I do my deep dives.
Ultimately, this is serious research that can take hours—or even days—of work. It’s the price you pay for an investment that you’ll be able to stick with over time, and that will help you avoid many mistakes and sleepless nights of doubt.
Final thoughts
In these three articles, we’ve seen the framework I use—and that I’m sharing with you—for selecting individual stocks. I develop investment cases whenever a stock seems like a great buy to me, based on a classification I outlined in another article. This method involves a detailed analysis, but this investment framework does not apply in every case. The next article will focus on how to identify companies on your own and how to screen them using an investment checklist to narrow down the field.
In addition, I invite you to check out the list of educational resources at the link below:

Disclaimer: This content is for educational purposes only and does not constitute investment advice — see our full disclaimer.